Код товара: 4211935469
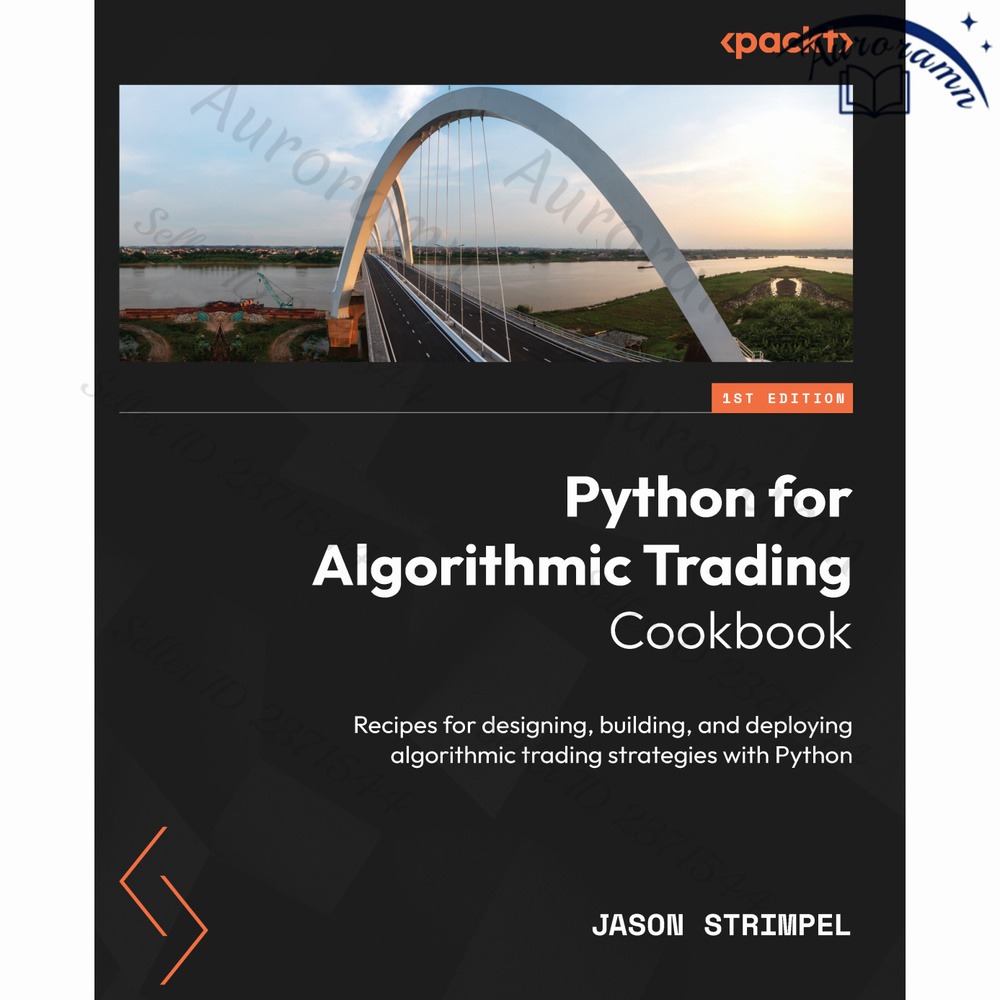
Python for Algorithmic Trading Cookbook: Recipes for designing, building, and deploying algorithmic trading strategies with Python
Тип книги:
Печатная книга
О товаре
Перейти к описанию
Автор на обложке
0
Год выпуска
2024
Тип бумаги в книге
Мелованная матовая
Тип обложки
Мягкая обложка
Тип книги
Печатная книга
О книге
Введение в книгу : Key benefits
Follow practical Python recipes to acquire, visualize, and store market data for market research
Design, backtest, and evaluate the performance of trading strategies us
2 308 ₽ 2 884 ₽
Магазин
Подписаться
Auroramn Library
Перейти4.7
Чат
О магазине
Часто задаваемые вопросы
Описание
Введение в книгу : Key benefits
Follow practical Python recipes to acquire, visualize, and store market data for market research
Design, backtest, and evaluate the performance of trading strategies using professional techniques
Deploy trading strategies built in Python to a live trading environment with API connectivity
Description
Discover how Python has made algorithmic trading accessible to non-professionals with unparalleled expertise and practical insights from Jason Strimpel, founder of PyQuant News and a seasoned professional with global experience in trading and risk management. This book guides you through from the basics of quantitative finance and data acquisition to advanced stages of backtesting and live trading. Detailed recipes will help you leverage the cutting-edge OpenBB SDK to gather freely available data for stocks, options, and futures, and build your own research environment using lightning-fast storage techniques like SQLite, HDF5, and ArcticDB. This book shows you how to use SciPy and statsmodels to identify alpha factors and hedge risk, and construct momentum and mean-reversion factors. You’ll optimize strategy parameters with walk-forward optimization using VectorBT and construct a production-ready backtest using Zipline Reloaded. Implementing all that you’ve learned, you’ll set up and deploy your algorithmic trading strategies in a live trading environment using the Interactive Brokers API, allowing you to stream tick-level data, submit orders, and retrieve portfolio details. By the end of this algorithmic trading book, you'll not only have grasped the essential concepts but also the practical skills needed to implement and execute sophisticated trading strategies using Python.
#данные
- Артикул
- 4211935469
- Автор на обложке
- 0
- Год выпуска
- 2024
- Тип бумаги в книге
- Мелованная матовая
- Тип обложки
- Мягкая обложка
- Тип книги
- Печатная книга
- Язык издания
- Английский
- Количество страниц
- 406
- Размер упаковки (Длина х Ширина х Высота), см
- 26*34*4
- Размеры, мм
- 251*179*25
- Вес товара, г
- 780
- ISBN
- 9781835087763
- Сохранность книги
- Очень хорошая
Подборки товаров в категории Научная и научно-популярная литература
Отзывы о товаре
0
Python for Algorithmic Trading Cookbook: Recipes for designing, building, and deploying algorithmic trading strategies with Python
Рейтинга пока нет. Он формируется на основе актуальных отзывов на заказанные и оплаченные товары
Как правильно задавать вопросы?
Будьте вежливы и спрашивайте о товаре, на карточке которого вы находитесь
Если вы обнаружили ошибку в описанием товара, воспользуйтесь функцией
Как отвечать на вопросы?
Отвечать на вопросы могут клиенты, купившие товар, и официальные представители.
Выбрать «Лучший ответ» может только автор вопроса, если именно этот ответ ему помог.